A version of this article first appeared in the CNBC Property Play newsletter with Diana Olick. Property Play covers new and evolving opportunities for the real estate investor, from individuals to venture capitalists, private equity funds, family offices, institutional investors and large public companies. Sign up to receive future editions, straight to your inbox.
Over the last few years, macro shocks have rocked the U.S. economy about every six months, from tariffs to the Iran war to the Democratic sweep of the midterm elections. All of that has a direct impact on real estate, according to Ryan Cotton, Bain Capital’s head of real estate.
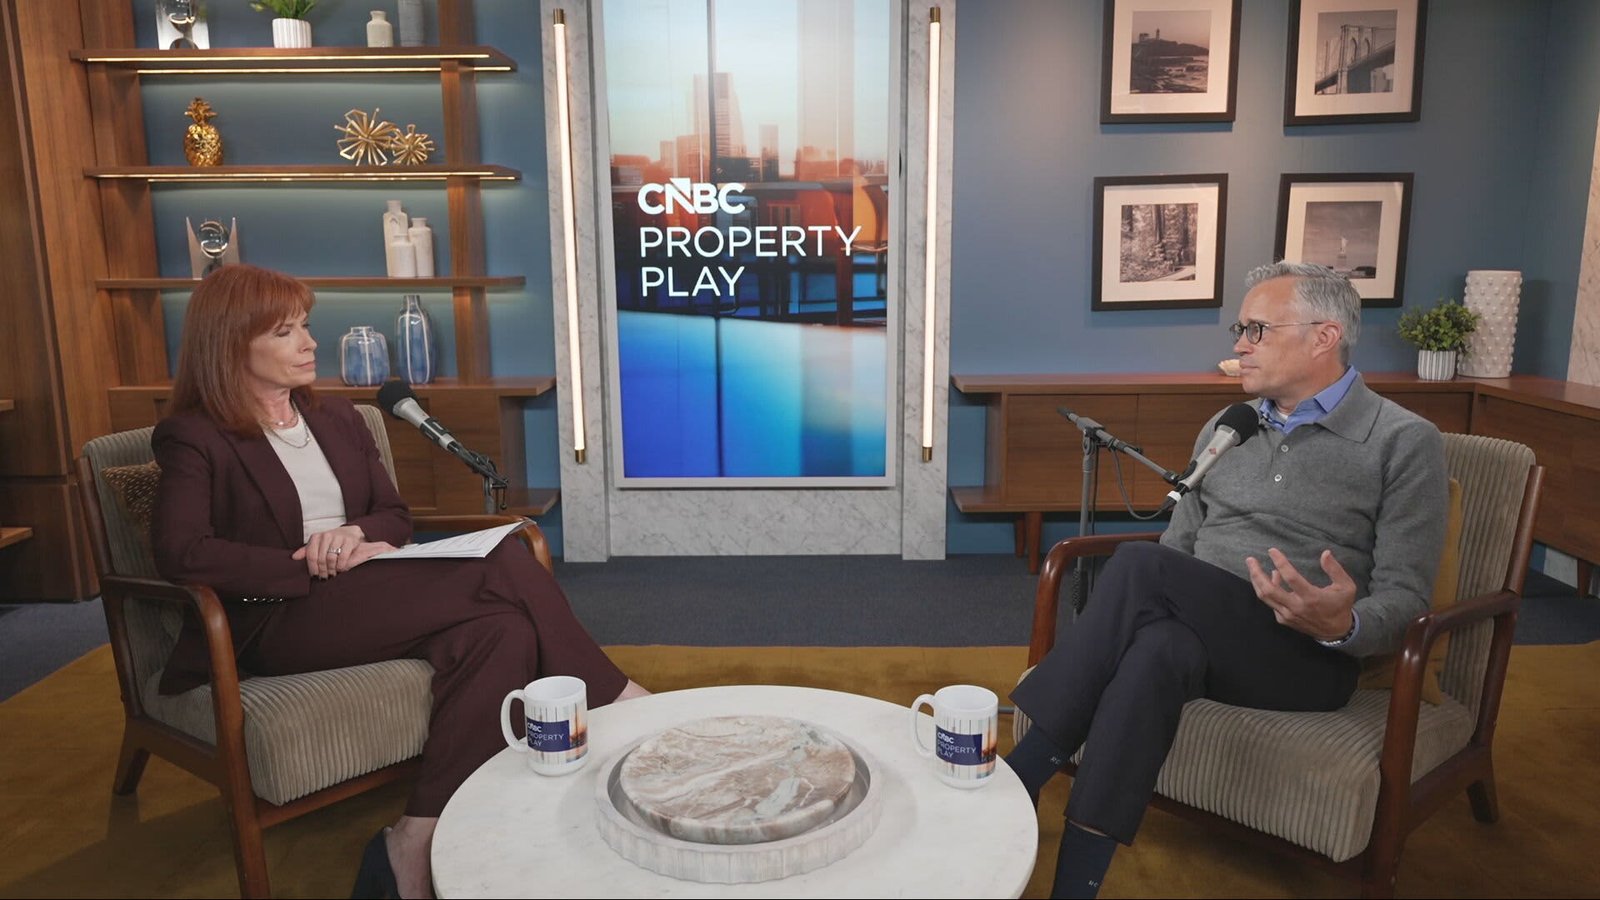
Cotton oversees $18 billion of real estate assets under management. In this week’s Property Play video podcast, Cotton says that every time the market starts to get back on its feet and find its balance and level, a new shock comes around, and there’s another digestion period that has to happen.
“I think it is disorienting as people try to rebase values, and in the midst of transactions, you’re seeing value retrades at the 11th hour, deals getting pulled, and volume slowing down yet again in the market,” said Cotton. “It’s definitely a confusing and complicated time to be a real estate investor.”
The overall market is still working through an oversupply in several sectors, which was brought on by extremely low interest rates at the start of this decade. There are also shifting demand patterns, with artificial intelligence changing the way logistics, supply chains, and offices work, and where wealth is being created and spent in the economy.
“All those things put together are creating this cocktail of disruption in real estate that’s made things disruptive for the industry as a whole, I think both in terms of understanding the value of what people own today in this new paradigm but also thinking about where do you go from here, and how do you allocate capital against those dynamic shifts?” Cotton said.
So how does Cotton navigate all that? He said Bain is a long-term investor, not a spot trader of assets. He looks at real estate over a ten-year period, evaluating the secular demand drivers that create the need for specific types of real estate.
“And if you take that lens, it leads you away from the office, it leads you away from the mall, it leads you candidly away from some multifamily markets where you have out-migration or oversupply of that product, and instead it leads you into more of what I would call alternative or emerging classes of real estate,” said Cotton.
Senior housing, self-storage and student housing are some of the more traditional but alternative classes he likes. But what really excites him are the super alternatives: Private airplane hangars and marinas for boats and yachts.
“Wealth is concentrating, and as people get richer, they buy more toys,” he explained. “It can generate double-digit NOI [net operating income] growth in those assets, and there is real scarcity of those assets and supply barriers. That means that even though demand continues to grow, supply may not have an adequate response to it.”
He points to recent deals involving Atlantic Aviation, the second-largest private airplane hangar platform in the U.S., and Safe Harbor, the largest marina platform in the country. The latter was bought by Blackstone this year.
Ten years ago, Cotton mused, something like 93% of all real estate assets in the world were invested in the four major food groups, being multifamily, office, retail and industrial. Now that’s down to 82%.
“More and more capital is moving out of those sectors, because of the lack of structural demand drivers, and moving into these more peripheral asset classes,” he said. “The 10 largest [REITs] in the world, seven of them are alternative sectors of real estate, be that data centers, be that senior housing. These are not traditional four food group asset classes, and that’s where the most liquid markets have migrated.”
Cotton leans on the idea of “Mr. Market,” a thought experiment invented by financial analyst Benjamin Graham and popularized by Warren Buffett to illustrate the swings of the stock market by imagining it as a person. “When he’s a bully, you can sell, and when he’s depressed you can just tell him to get out of your office,” said Cotton. “If you put your head down and work hard on creating value, I’m certain that eventually the market finds its level, finds its balance, and Mr. Market finds his optimism again, and then you can get back into transacting.”